By Duane Buziak, NMLS #1110647. Glen Allen, Short Pump and Henrico buyers sometimes lose a contract because a mortgage contact took a day to return a call or a document request. This guide ranks six options on how quickly and clearly they communicate, using published contact channels, process design and local availability as the criteria. It is written for first-time buyers, move-up buyers and refinancers in Innsbrook, Twin Hickory, Wyndham and Tuckahoe. I have not asserted response times, awards or reviews for any competitor, because I have no verified data on them. Details below are hedged “as of October 2026,” so confirm them on each company’s official site.
- Quick comparison and responsiveness table
- 1. Glen Allen Mortgage by Duane Buziak
- 2. Rocket
- 3. Movement
- 4. Alcova
- 5. Sparrow Home Loans
- 6. Cowart Team
- How to test responsiveness before you commit
- Frequently asked questions
- Matching the right option to your situation
Quick Comparison of Six Mortgage Options
- Glen Allen Mortgage by Duane Buziak: Glen Allen and Henrico buyers wanting one local contact; free No Touch Credit review; a named local broker plus a soft-pull review before any hard inquiry.
- Rocket: buyers who prefer to manage everything online; see website for pricing; self-service digital tracking that works without a phone call.
- Movement: buyers wanting a national company with a personal contact; see website for pricing; a named loan officer paired with a digital portal.
- Alcova: Virginia buyers wanting a regional team; see website for pricing; regional familiarity with Virginia closings (verify).
- Sparrow Home Loans: buyers weighing a smaller team against a national name; see website for pricing; possible small-team access (verify).
- Cowart Team: buyers who value team coverage over one officer; see website for pricing; coverage not tied to a single person (verify).
| Option | Named contact | Self-service portal or app | Soft-pull start | What to verify |
|---|---|---|---|---|
| Glen Allen Mortgage by Duane Buziak | Yes, Duane Buziak directly | Document requests handled with Duane’s practice | Yes, Free No Touch Credit review | Availability during peak rate-driven volume |
| Rocket | Often a team, not one person | Yes, app and online upload with status tracking | Ask before applying | Who your day-to-day contact will be |
| Movement | Branch loan officer | Yes, online borrower portal | Ask before applying | Branch and officer experience |
| Alcova | Verify | Verify | Ask before applying | Digital tools, product range, hours |
| Sparrow Home Loans | Verify | Verify | Ask before applying | Virginia service area and licensing |
| Cowart Team | Team coverage (verify) | Verify | Ask before applying | Richmond-area service and licensing |
1. Glen Allen Mortgage by Duane Buziak
Glen Allen Mortgage by Duane Buziak is a local broker practice led by Duane Buziak, NMLS #1110647, operating through Coast2Coast Mortgage LLC (NMLS #376205) from 4860 Cox Rd in Glen Allen. It serves buyers and homeowners across Glen Allen, Short Pump and Henrico, from Wyndham to Lakeside. I list it first because I run it, so weigh that accordingly and use the checklist later in this article to test me too.
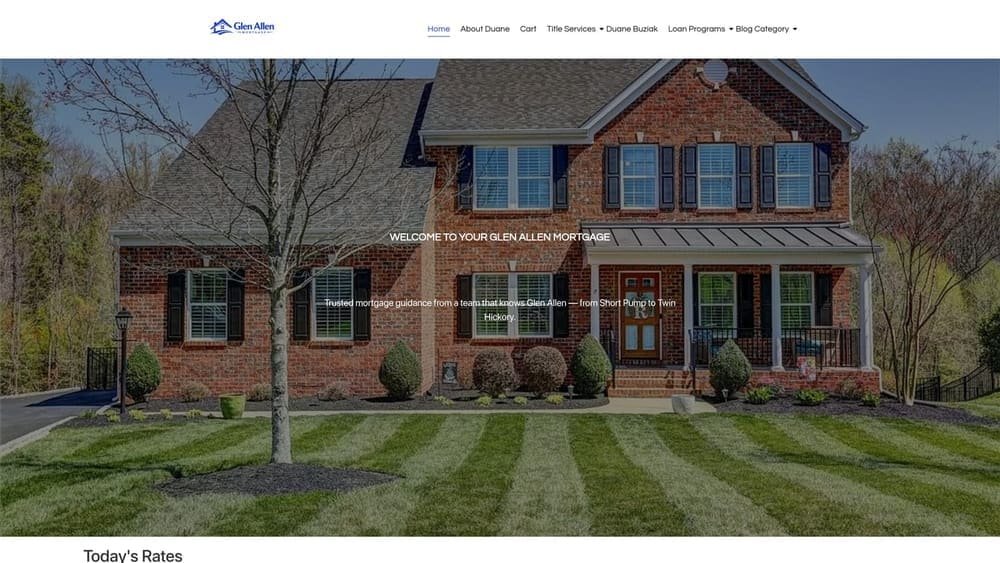
What sets it apart on this list is structure: one named person, and a soft-pull start. The Free No Touch Credit review is a soft credit pull mortgage review, so you can see where you stand without a hard inquiry on your report. Full underwriting does eventually require a hard pull, but you choose when that happens.
- Home purchase, refinance, FHA, VA, renovation and commercial loans, so one conversation covers most scenarios.
- Free No Touch Credit review, which lets you start without a hard inquiry.
- Shopping of many wholesale options at once, so you are not waiting on a single product shelf.
- Direct access to Duane Buziak, so a deadline question goes to the person who knows your file.
- Realtor referral relationships, which help your agent and your broker coordinate quickly.
Setup is light: a conversation, then document collection. Duane runs your file day to day, and agents in the area are a common route in.
The limitation is size. This is a small local practice, and one person cannot be everywhere during a rate-driven rush, so ask about availability when your offer deadline is close. There is no portal-only, no-conversation option if you want a fully self-service process.
Pricing: the credit review is free, with no upfront fee. Loan costs depend on loan amount, program and your profile; ask about our no-out-of-pocket closing options and see the website for details.
Best for: Glen Allen and Henrico buyers who want one local contact and a credit-safe start.
2. Rocket
Rocket is a large, digital-first national mortgage company built around an app and online application. It is designed for buyers who would rather upload a pay stub at 10 p.m. than schedule a call.
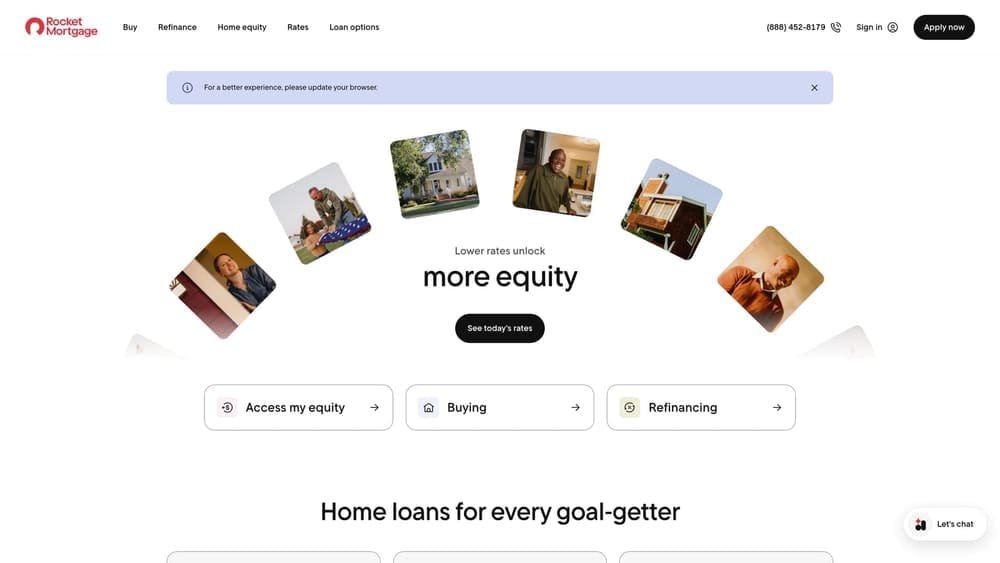
Its strength is self-service visibility. You can see what has been requested and what is outstanding without calling anyone, which removes one common source of delay: waiting to learn what is missing.
- Online and app application, so you can start from your phone.
- Document upload and status tracking, so you see what is outstanding without phoning.
- Purchase and refinance programs covering the common scenarios.
- Rate and payment tools to test scenarios before you commit.
Setup runs through the mobile app and online document upload; you run most of it yourself. That suits organized, comfortable-with-technology borrowers.
The limitation to weigh is the handoff model. Team-based processing can mean no single dedicated contact, so a question about a specific appraisal issue may reach a queue rather than a named person. I have no verified response-time data for Rocket, so ask who your contact is and how to reach them after hours before you apply.
Pricing: see website. As of October 2026 I am not quoting figures; rates and costs depend on loan size, credit profile and program.
Best for: Buyers who prefer to manage the process online.
3. Movement
Movement is a national retail mortgage company that pairs branch-based loan officers with online application tools. The pitch is a person plus a portal.
Where it stands out
Among the national names here, Movement most clearly combines a named loan officer with a digital portal. If you want to text-style quick answers from a person but also upload documents online at night, that combination fits.
Features
- Branch-based loan officers, giving you a face and a number rather than a queue.
- Online application and portal, so documents move without email attachments.
- Purchase and refinance programs for typical home-buying situations.
Setup, limits and cost
Setup involves choosing or being matched with a loan officer, then using the borrower portal. The loan officer runs the relationship; the portal handles paperwork.
The main limitation is variability. Experience depends on the branch and the individual officer, so a national brand name tells you little about your own file. Before committing, ask the officer how they handle weekend questions, who covers when they are out and how fast they turn a pre-approval. I have not verified Movement’s hours or turnaround times.
Pricing: see website. Costs vary with loan amount, program and credit profile.
Best for: Buyers wanting a national company with a personal contact.
4. Alcova
Alcova is a mortgage company with a Virginia-area presence. I have not verified its details, so treat everything here as a checklist to confirm on its official site as of October 2026.
The potential advantage is regional familiarity: a team accustomed to Virginia closings, local title practices and nearby appraisers can reduce friction when a deadline is live. Whether that holds for Alcova is something to confirm in conversation.
Items to verify:
- Regional Virginia focus, which matters if you want people who know Henrico-area closings.
- Purchase and refinance programs, so you know your loan type is covered (FHA, VA, renovation).
- Local loan officers, and whether you get one named person.
Ask who your point of contact is, what channels they answer on, whether there is a document portal, and what their typical pre-approval turnaround is. Setup effort and integrations are not confirmed here; see the website.
The limitation is uncertainty: digital tools and product range need verification, and I cannot say whether it offers a soft-pull start. If you want a mobile app experience, confirm one exists before assuming it does.
Pricing: see website. Request a written estimate so you can compare it against the others on equal terms.
Best for: Virginia buyers who want a regionally based team.
5. Sparrow Home Loans
Sparrow Home Loans is a mortgage company whose business model, service area and programs I have not verified. Check its official site as of October 2026 before relying on anything here.
The reason to include it is the smaller-team question. A small team can mean direct access to the person handling your file, which is often what speeds up a stalled document request. That is only an advantage if the site and the people confirm it.
Confirm these points:
- Home purchase and refinance programs, including any FHA or VA options you need.
- Direct loan officer contact, and by which channel (phone, text, email).
- Online application, and whether documents can be uploaded securely.
The key limitation is that Virginia service area and licensing need verification. A company must be licensed in Virginia to originate your loan, so ask for its license details up front. You can look up individual originators by NMLS number through the public NMLS Consumer Access site.
Setup effort and integrations are unconfirmed; ask whether a portal exists or whether everything runs by email. Smaller teams can also have thinner coverage when someone is out, so ask who covers.
Pricing: see website. Fees depend on program and loan size; ask for a Loan Estimate to compare.
Best for: Buyers comparing a smaller team’s direct access against a national company.
6. Cowart Team
Cowart Team is a team-based mortgage group. Its location, licensing and programs have not been verified here, so confirm them on its official site as of October 2026.
The argument for a team model is coverage. If a single officer is at a closing or on vacation, someone else can pick up your call. For a buyer with a tight appraisal or inspection window, that continuity can matter more than a single relationship.
- Team-based service, which may mean someone is available when your main contact is not (verify).
- Purchase and refinance programs for typical scenarios (verify).
- Local market focus, which helps if the team knows Richmond-area practices (verify).
The tradeoff is the one named in the plan: you may not get a single point of contact, and different people may answer the same question differently. Richmond-area service also needs verification; a team that is excellent elsewhere may not be licensed or active here. Ask how files are assigned, who is accountable for your timeline and whether there is a client portal.
Setup effort and integrations were not confirmed; see the website.
Pricing: see website. Ask for a written estimate and compare it with the others.
Best for: Buyers who value team coverage over one dedicated officer.
How to Test Responsiveness Before You Commit
The biggest national brand is not automatically fastest. Speed depends on the individual officer and your file, so test it. The CFPB’s Owning a Home resources explain the process and the Loan Estimate you should request from each company.
- Send the same question to each company on the same afternoon and note how long a useful answer takes.
- Ask for a named contact, a backup, and the hours they answer.
- Ask what the document portal does and whether it shows outstanding items.
- Ask for pre-approval turnaround in writing, and whether a mortgage pre approval without hard pull is available as a first step.
- Ask who handles an appraisal issue or a contract deadline extension.
On credit: a soft pull does not affect your scores, while a hard inquiry can, and full underwriting requires one. Starting with a soft look avoids stacking inquiries while you compare. Rate shopping within a short window is generally treated as one inquiry for scoring, but check the current guidance rather than assuming.
A worked example, as an illustration
Suppose you buy a $450,000 home near Innsbrook with 10% down. That is $45,000 down and a $405,000 loan, well under the 2026 conforming limit of $832,750 that FHFA sets for most of the country, which includes Henrico. At an assumed 6.50% on a 30-year fixed, principal and interest comes to roughly $2,560 a month. That rate is purely illustrative; check the Freddie Mac Primary Mortgage Market Survey for current averages. If a slow reply costs a week in a rising market, even a quarter-point move on that loan is roughly $65 a month, which is why speed has a dollar value.
Frequently Asked Questions About Responsive Mortgage Companies
1. What makes a mortgage company responsive? Responsiveness means a named contact, clear hours, a document portal and written turnaround times. Marketing claims alone do not prove it; test it with a same-day question.
2. Is the biggest national company always the fastest? No. Speed depends on the officer, team capacity and the complexity of your file, not the brand size.
3. Can I get a mortgage pre-approval in Glen Allen without a hard credit pull? You can start with a soft look. Duane Buziak offers a Free No Touch Credit review, and full underwriting later requires a hard pull.
4. How does the NoTouch Credit Pull work with Duane Buziak? It is a soft-pull review of your credit profile, so your scores are not affected. It shows where you stand before any hard inquiry.
5. What is the difference between a soft pull and a hard inquiry? A soft pull does not affect your scores and is used for review. A hard inquiry is required for formal underwriting and can affect scores slightly.
6. What is the 2026 conforming loan limit? The baseline limit is $832,750 for one-unit properties, per FHFA. Confirm it on the FHFA site before you rely on it.
7. Is Duane Buziak a legitimate mortgage broker in Glen Allen? Yes. Duane Buziak is NMLS #1110647, operating through Coast2Coast Mortgage LLC, NMLS #376205, and you can verify both on the NMLS Consumer Access site.
8. Is it better to use a broker or go direct to a national company? A broker can compare many wholesale options with one application, while a direct company offers its own products and tools. Responsiveness varies in both cases, so test it.
9. Does GlenAllenMortgage.com serve Short Pump, Twin Hickory and Wyndham? Yes. GlenAllenMortgage.com serves Glen Allen, Short Pump, Innsbrook, Twin Hickory, Wyndham, West Broad Village, Tuckahoe and Lakeside.
10. What should I ask before choosing a company? Ask for your contact’s name, backup coverage, hours, portal features, pre-approval turnaround and a Loan Estimate you can compare.
Matching the Right Option to Your Situation
For a first-time Henrico buyer, I would start with a conversation and a credit-safe review: Duane Buziak at Glen Allen Mortgage, because one named person walks you through each step. For a fast-moving offer, favor whoever gives you a named contact, a backup and written turnaround, which could be Duane, a Movement loan officer or a team model like Cowart Team once verified. For a digital-only borrower, Rocket’s app and status tracking fit best. If you prefer a regional team, check Alcova and Sparrow Home Loans against the verification list above.
Ready to experience stress-free mortgage approval with no credit hit and access to hundreds of wholesale options at once? Get your free mortgage consultation today and discover why Glen Allen families trust Duane Buziak for personalized guidance and the fastest close times in the area. Call Duane Buziak at 804-212-8663 for a free No Touch Credit check.

